Divorced Gals Editorial
Who Gets the House in Divorce?
There are divorce questions, and then there is the divorce question. Who gets the house in divorce?
Not the sofa. Not the dishes. Not the suspiciously expensive Peloton no one used after February. The HOUSE.
The marital home is rarely just real estate. It holds memories, routines, a sense of stability, and is often one of the largest assets in a marriage.
What feels like security to one spouse may feel like financial pressure to the other. And that is exactly what makes this decision so personal—and so complicated.
Forget the courtroom myths and internet clichés.
Remember: no one automatically "wins" the house. Who keeps the house after divorce depends on law, finances, negotiation, your children's needs—and one very practical question:
What choice still makes sense six months from now?
Why Marital Home Matters So Much?
People often think divorce fights are about property. But the fight over the house is usually about much more than the house itself.
The home may be where your children learned to walk. Where you celebrated birthdays, painted walls, planted trees, hosted holidays, and built a version of the future you believed in.
So when someone says, "I want to keep the house," they may really mean:
I want life to feel recognizable.
I want my children to feel safe.
I do not want to lose everything at once.
Those feelings are real. They matter.
But the decision still has to work financially. The mortgage, taxes, insurance, repairs, and everyday cost of keeping the home matter too.
———
Wisdom lives where emotion
and math finally meet.
So where does that leave the house.
Who Gets the Hose In Divorce? The Real Answer
There is no universal rule that says the wife gets the house, the higher earner, or the spouse whose name is on the deed.
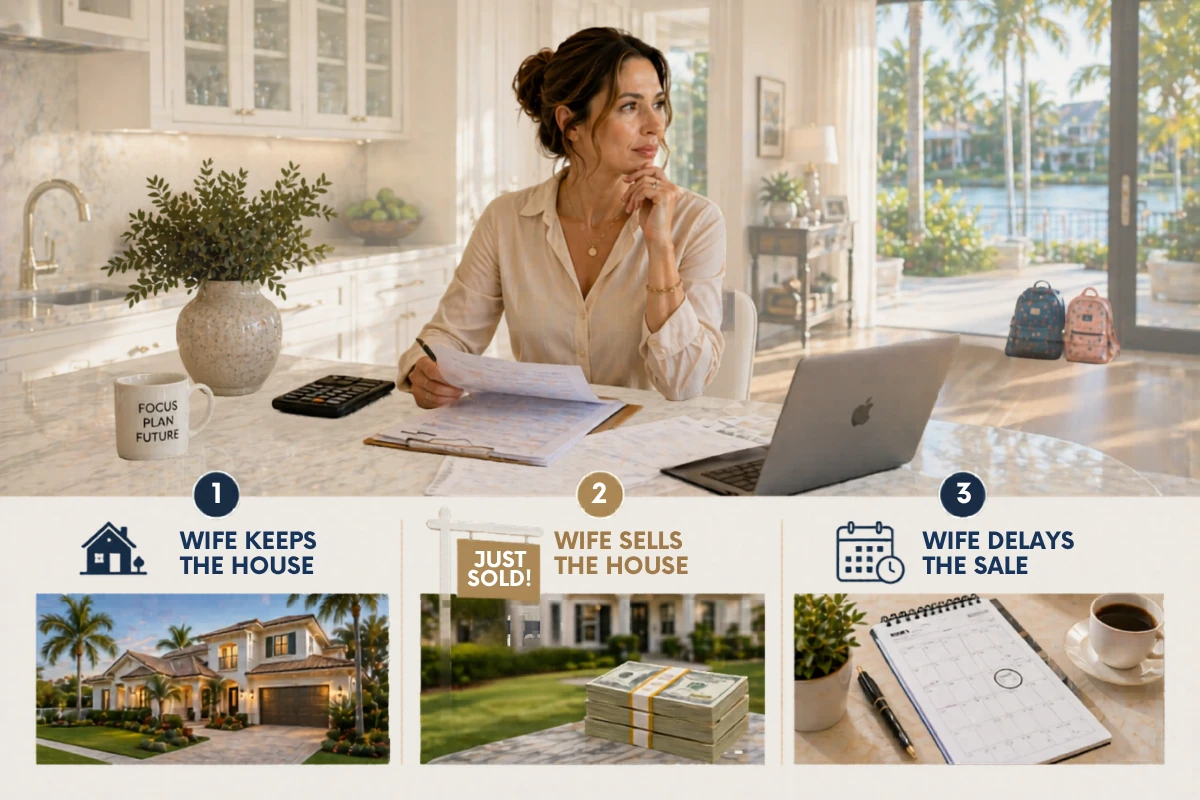
In most divorces, one of four things happens.
- One spouse keeps the house and compensates the other for their share. This is commonly called a "buyout."
- The house is sold and the proceeds are divided.
- One spouse stays in the house temporarily, and the property is sold later. The agreement determines how the proceeds will eventually be divided.
- The home becomes part of a larger negotiation about how other assets are divided.
So, if you keep the house, do you simply take over the mortgage?
Not necessarily. If you receive more of the home equity, your spouse may receive more cash, investments, retirement assets, or other property as part of the settlement.
But if the numbers are equal, isn't that fair?
Not always. A house, a retirement account, and an investment portfolio may look equal on paper but work very differently in real life. They come with different costs, taxes, access to cash, and opportunities for the future.
That last point matters more than many people realize.
Sometimes the question is not "Who gets the house?" but "What are we each getting overall?"
A house is one asset. A fair settlement is the bigger picture.
What Courts and Settlements Actually Consider?
So, what actually determines who gets the house in divorce?
Whether a judge decides what happens to the house or you reach an agreement through negotiation, many of the same practical questions come up:
- What works for the children?
- Who can realistically afford the house?
- How much equity is at stake?
- And if you keep the house, what does it mean?
Then there are the children. Staying in the home may mean keeping the same school, neighborhood, and familiar routine. But stability is only the beginning of the story. Someone still has to be able to afford the house.
Another consideration is income, and income matters. Why?
You may love the home deeply and still be unable to comfortably carry the mortgage, property taxes, insurance, maintenance, and repairs on one income.
Equity matters too. The more equity you have in the home, the more you may have to give up elsewhere in the settlement. That solves one question while creating another: What are you giving up to keep the house?
The history of the house matters too. When did you buy the house? Whose name is on the title? How did you pay for the house: with marital or separate funds? The answers can matter depending on your circumstances and state law.
And then there is the mortgage—the least romantic character in the entire story. A divorce settlement may say that one spouse keeps the house. But that doesn't mean the lender will remove the other spouse from the loan or approve a refinance.
So, in summary: wanting the house, receiving the house, and being financially able to keep the house are three different things.
And in the end, the question isn't who wants it most. It's which plan actually works.
How might it work in real life?
A Florida Example: Three Possible Outcomes
Imagine a Boca Raton couple, Elena and David.
Their home is worth $1,200,000 with a remaining mortgage of $450,000. They have one child in middle school.
Elena would like to stay in the home for another two years so their daughter can keep the same school and have a familiar routine. David, on the other hand, would prefer to sell the house now and divide the equity.
Both positions make sense. So, how would Florida law look at this?
First, Florida follows so-called equitable distribution principles. What does that mean?
For marital assets and debts, the court generally starts with an equal division, unless the circumstances call for a different result.
Second, when the marital home is involved, the family's finances and the needs of a dependent child become part of the decision.
So, what could Elena and David do?
Option 1: Sell later
Elena stays in the home for two years, and then they sell it and divide the proceeds as agreed. Of course, David and Elena need to decide who pays the mortgage, property taxes, insurance, maintenance, and repairs while Elena is living there.
Option 2: Buyout
Elena keeps the house and buys out David's share. That means qualifying for the mortgage on her own and deciding how to pay David.
Option 3: Sell now
Elena and David sell the house now and divide the proceeds. As a result, they each have access to their share of the equity and don't have to manage the house together for another two years.
Three options. Three very different financial outcomes.
As you can see, understanding your options is one thing. Knowing which one actually works for you is another.
And sometimes, when spouses can't agree, a court has to decide.
Court Decision: When Staying in the Home Makes Sense
Note that Florida law provides us the framework. Case law, in turn, shows how it can work in real life.
Zeller v. Zeller is a good example—a Florida divorce case involving a family with two young children.
The question here wasn't simply whether the marital home would eventually be sold. It was WHEN the home would be sold.
The trial court allowed the wife to stay in the marital home for three years. After that, the house would be sold.
Yes, three years may sound reasonable. But the appellate court saw it differently. Why? Because the children—only five and six at the time of the divorce—would still be quite young three years later.
The court also looked at the family's finances and what it would mean for the children to have to move again. In this case, the court allowed the wife to stay in the home until the younger child turned 18—the age of majority in Florida.
And that is what makes Zeller worth our attention. The wife didn't simply "get the house." The house would eventually be sold. What changed was the TIMING.
In other words, the question was whether selling the marital home now—or later—made more sense for this family.
Well, Zeller v. Zeller goes back to 1981. Florida law today follows the same basic idea. Keeping a child in the marital home may make sense—but only if it is in the child's best interest and the family can afford it.
The lesson here is not that the parent with children gets the house.
Sometimes the timing of a sale matters—especially when young children are still living at home.
And sometimes, the decision about the house is a part of a much bigger question: What happens to everything else?
Celebrity Example: Even Millionaires Face the Same Question
For an extreme example, look at a celebrity divorce. The numbers may be much larger, but the underlying financial questions can look very familiar.
Take, for example, Julia Haart and Silvio Scaglia. She was a fashion executive and CEO of Elite World Group. He was an entrepreneur and investor. They were not only married but they also were business partners and had deep financial ties.
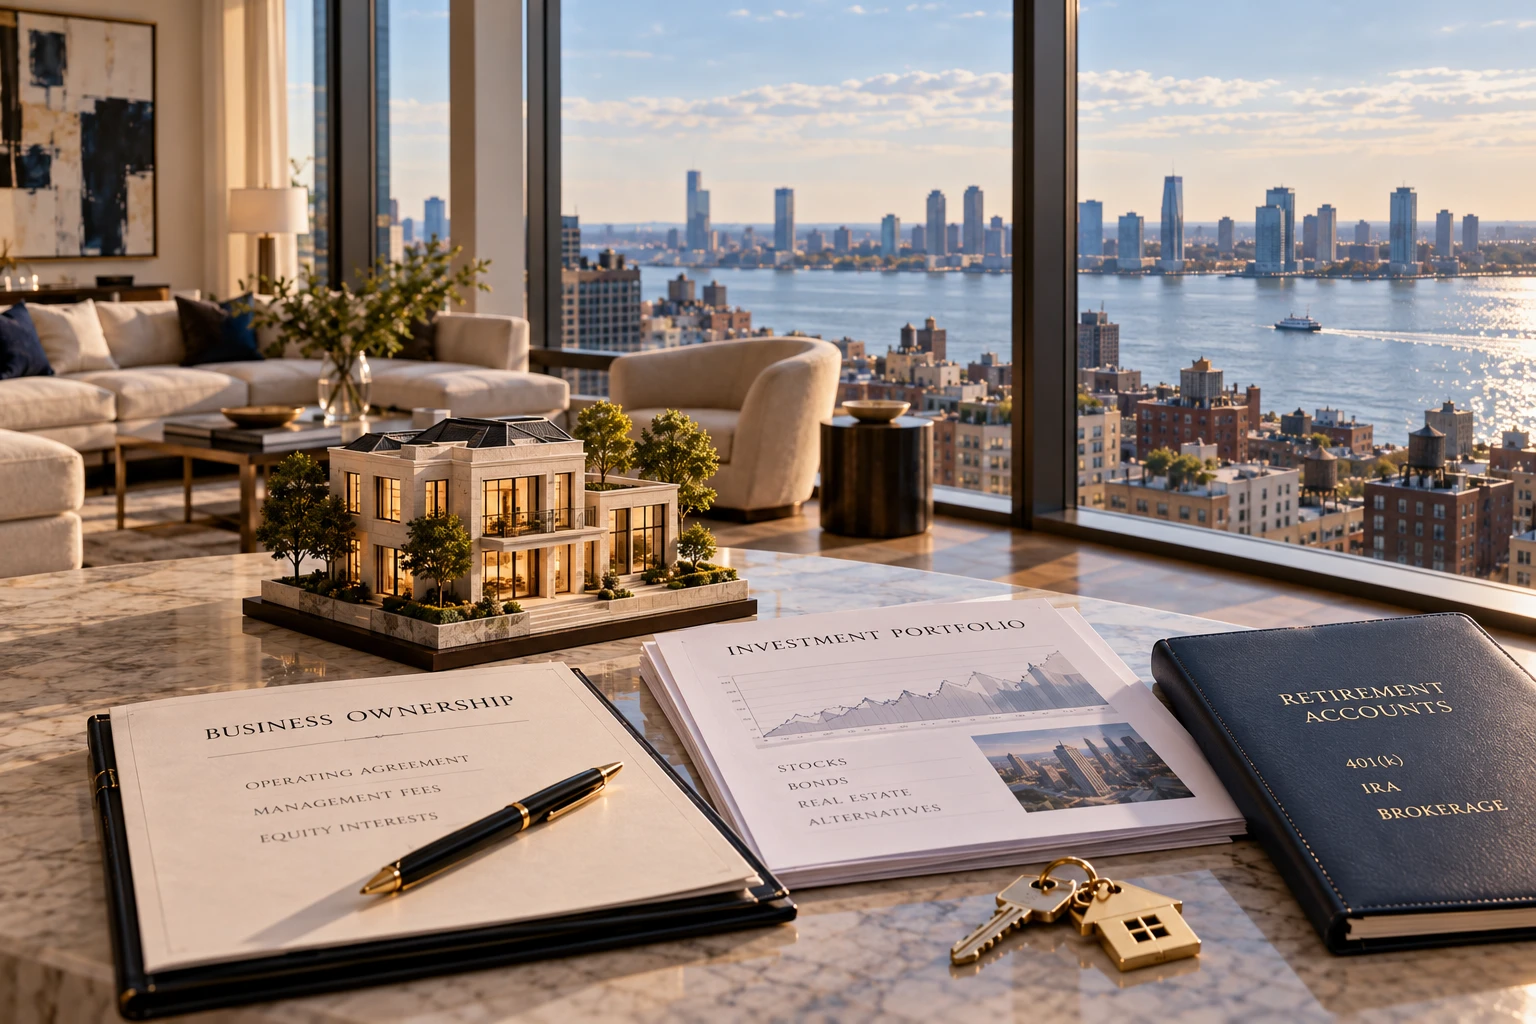
When Julia and Silvio were going through a divorce, there was a lot more at stake than their multimillion-dollar home in Tribeca. They argued about business ownership, management fees, artwork, and other valuable assets.
Yes, their home was worth a fortune. But they couldn't make decisions about the house without looking at everything else.
The moral of the story?
Whether your home is worth $600,000 or $60 million, the same questions apply.
- If you want to keep the house, what will you have to give up?
- How much cash would you be left with?
- And in the end, if you keep the house, are you better off?
Well, money can change the scale. It does not change the logic.
Should You Keep the House?
Sometimes yes.
In this case, your children stay in the same school, keep their familiar routines, and don't have to move right away. And sometimes, staying in the house simply feels right.
But a beautiful home can become a burden very quickly if every month you feel financially tight.
So, before you decide to keep the house, ask yourself why you want it. Does it really work for your life after divorce—or is it simply hard to let it go?
That is not the same decision.
Next, what would it actually cost you to keep the house?
KEEPING THE HOUSE
Look Beyond the Mortgage
More than just the mortgage. Include property taxes, insurance, utilities, maintenance, and repairs.
Ask yourself if your income and savings can comfortably cover the full cost, including unexpected repairs.
Keeping the house may mean giving your spouse a larger share of other assets, such as cash, investments, or retirement accounts.
Consider the bigger picture. What might you have to give up - in cash, investments, or part of a 401(k) - to keep the house?
Start with the obvious: the mortgage, property taxes, insurance, utilities, maintenance, repairs. Can you comfortably afford it?
But! There is more to the cost of keeping the house. What will you have to give up in return—more cash, investments, part of your 401(k) plan?
At the end of the day, you can own a valuable home and still find yourself short on cash.
And what about the mortgage?
If both of your names are on the loan, your divorce settlement doesn't automatically take one of you off. So, before you make plans to stay in the house, find out what your lender will require.
And finally, what if you sold the house instead?
How much cash would you have available?
What could you afford to buy—or maybe rent?
Would that give you more financial breathing room?
In summary, the right question is not simply:
Can I keep the house?
THE BETTER QUESTION:
Can I keep the house and still have enough money for everything else?
And this is where our Certified Divorce Financial Analyst® can help to analyze your options and compare the numbers behind them.
When Selling the Marital Home Is the Smarter Move
People often see selling the marital home as a defeat.
Well, it is not.
Sometimes the house has simply become too expensive to keep.
So, what happens if you sell?
For one thing, you may finally have access to the money tied up in the house. And that can prevent a common trap: becoming house-rich and cash-poor. Familiar?
Or maybe you can afford to keep the house. But how much room would that leave for everything else? Well, if keeping it makes you feel tight on cash, doesn't selling make more sense?
Also, selling the house can mean you deal with your ex much less and have the freedom to decide your next step. And sometimes selling buys you something the house cannot:
flexibility.
And remember: the sale price is not what you walk away with. First come the mortgage, selling costs, and possibly taxes. What's left is the money you actually have to work with.
Of course, selling the house is not only about the numbers.
You may still be saying goodbye to the kitchen where everyone gathered, the backyard where your children played, or the home you once expected to grow old in. And that's why even when selling makes financial sense, it can still feel like a loss.
But letting go of the house can also make room for something new. What could that look like?
A home that costs less to maintain. More cash when you need it. Or simply not having so much of your money tied up in one place.
And sometimes, a smaller home can feel far more luxurious. Because peace doesn't always mean staying in the house you love.
Sometimes it arrives in a moving truck.
FAQ
No. A wife doesn't automatically get the house in divorce. It depends on your finances, who bought the house and when, and how the house fits into the rest of your divorce settlement.
Having both names on the deed matters, but the deed alone doesn't decide what happens to the house in divorce. Other questions matter too:
- When did you buy the house?
- How did you pay for it?
- Did either of you own the house before marriage?
- How much equity is in the house?
- Is there a mortgage, and whose names are on the loan?
- Can either of you afford to keep the house?
- Do you have children living in the home?
- What other assets are being divided?
So, having both names on the deed matters, but it doesn't decide what happens to the house in divorce.
Sometimes. If you stay in the house, your children can keep the same school and neighborhood, be closer to their friends, and have a familiar routine.
In other words, keeping the house may be in your children's best interests, but the numbers still have to work.
Yes. You may be able to keep the house without refinancing. Your loan terms will tell if you can assume the existing loan instead.
But if your former spouse is also a borrower on the mortgage note, there is another issue. Your divorce settlement doesn't simply release your ex from their obligation for the loan.
For this, you should contact your lender and ask if you can assume the loan and if they will release your spouse from liability. Note that you may also have to qualify for the loan on your own.
If neither of you can afford to keep the house after a divorce, selling may make the most sense. Once you pay off the mortgage and selling costs, you can divide what is left.
Yes, it may be difficult to sell a marital house you love. But keeping a house you cannot afford can be even harder.
Final Thoughts
By now, you probably know that "Who gets the house in divorce?" is not really one question.
It is about your children. Your money. Your mortgage. What you may have to give up. And, yes, what the house means to you.
But here is something else worth remembering:
———
The house is part of your story. It doesn't have to be the ending.
Maybe you keep it. Maybe you sell it. Maybe you move somewhere smaller and find out that smaller might feel surprisingly good.
Whatever you decide, come back to the question we asked at the beginning:
What choice will still make sense six months from now?
Because six months from now, this house may look very different to you. And so may the life you're building after divorce.
And if you are trying to figure out what keeping—or selling—the house would actually mean for you, let's look at the numbers together.
For the life you're building,
Nella Zelensky
About the Author
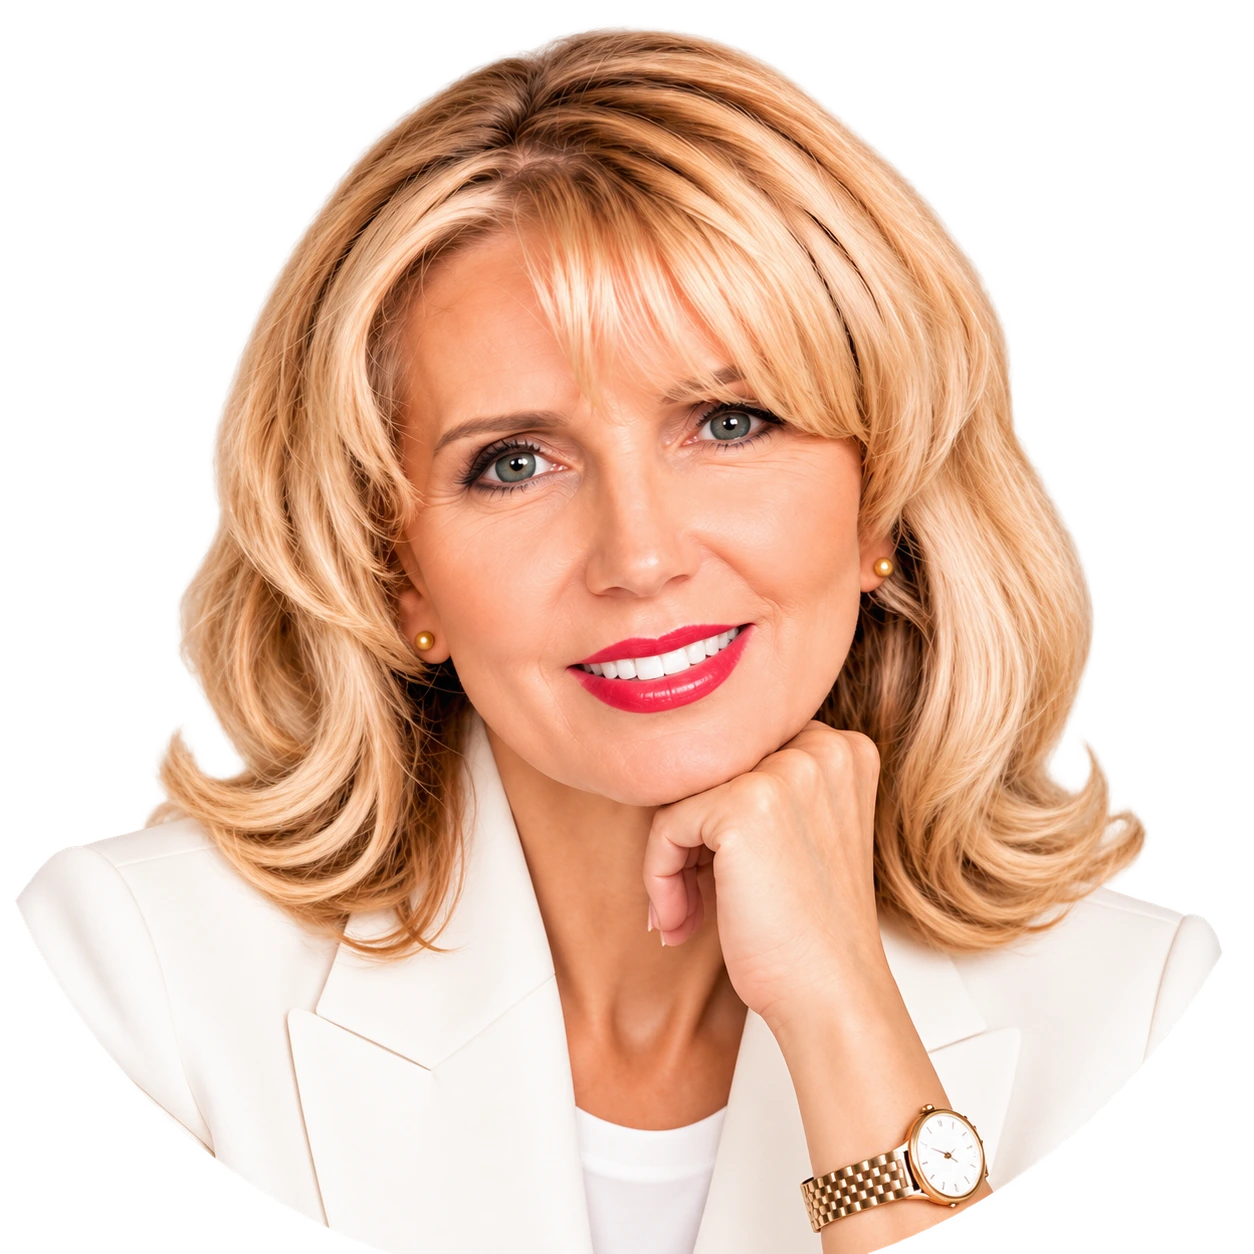
Nella Zelensky, CDFA®, MAFF®
Facing her own divorce, Nella discovered firsthand how overwhelming financial decisions can become—even with a background in finance. That experience inspired her to focus on divorce financial analysis. Building on an established career in finance, she earned the Certified Divorce Financial Analyst® (CDFA®) designation, followed by the Master Analyst in Financial Forensics® (MAFF®) credential.
Today, as Co-Founder of The Divorced Gals, Nella helps women understand the financial consequences of divorce, ask better questions, and make decisions with greater clarity and confidence.
