
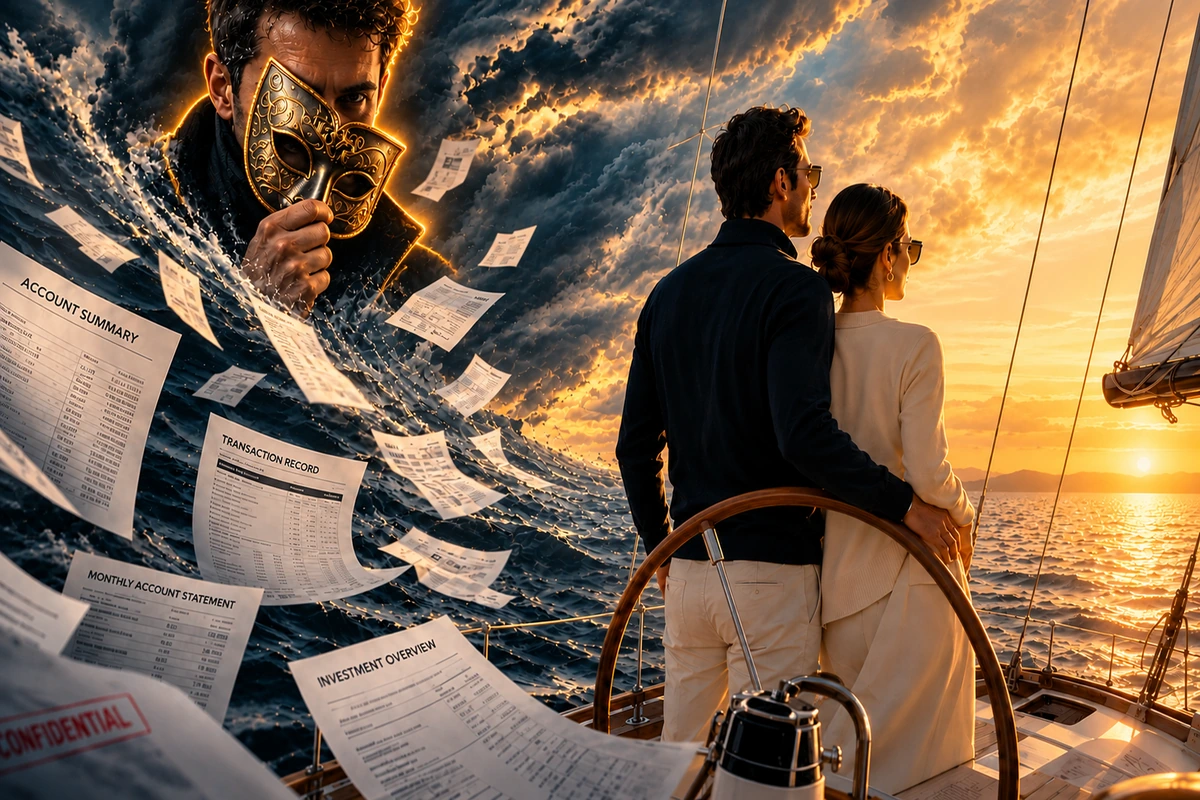
You are happily married, and with your spouse, you are sailing through life, basking in the glow of love. But beneath the tranquil surface lies a lurking danger, and one day, you find yourself in treacherous waters of financial infidelity.
What happened?
You accidentally discovered a bank statement with your spouse's name on it that you had no clue about. Will you think of betrayal? Would it rack your boat? Would it ruin your marriage?
Yes, today's topic is that sneaky little devil who can wreak havoc on your happy marriage and your hard-earned cash. But don't worry!
This post will equip you with the knowledge, tools, and even a sprinkle of humor to sail through this storm and emerge stronger on the other side.
Ready?
What Is Financial Infidelity?
First, let's have an understanding of financial infidelity in couple relationships.
Remember, when people get married, most of them combine finances. Therefore, when handling money, they promise transparency and cooperation.
Unfortunately, it doesn't always work this way. As a result, a spouse might deceive you by hiding money, inheritance, assets, receipts, bills, or other evidence of their financial misbehavior.
And here, you are not alone.
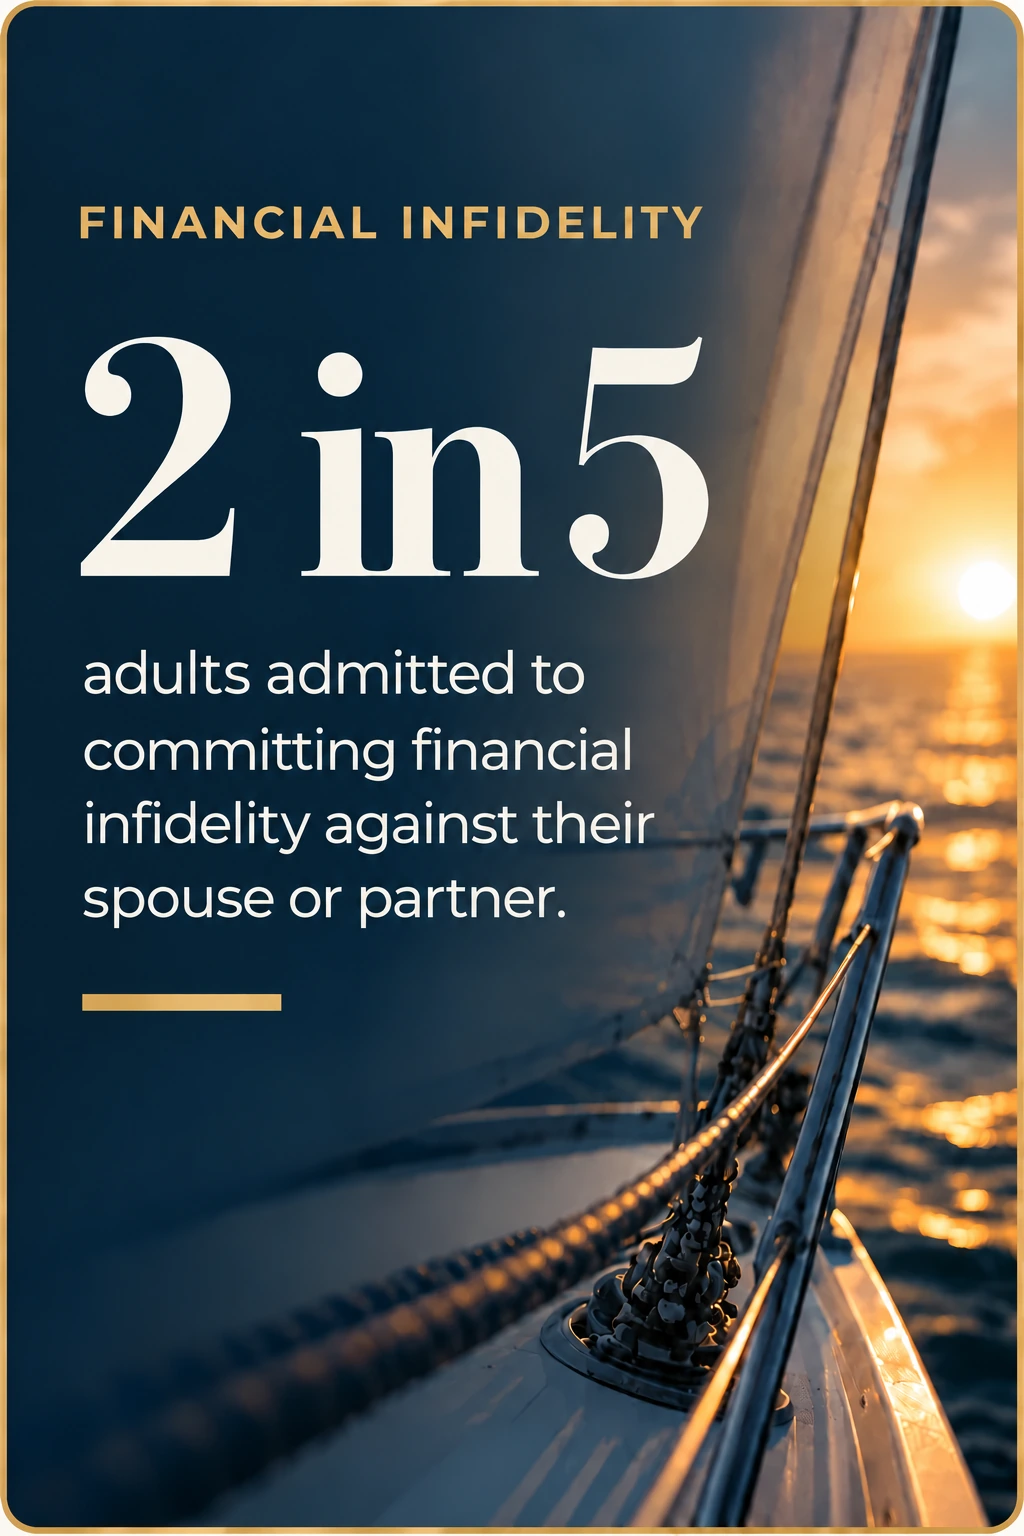
According to a 2021 survey by the National Endowment for Financial Education (NEFE), 43% of U.S. adults who had combined finances with a spouse or partner admitted to financial deception. That's roughly two in five adults.
And financial deception rarely stays just about money. In the same survey, 85% of those who experienced it said it affected their relationship.
What Causes Financial Infidelity?
When one spouse controls the finances, the other might secretly spend money as an act of defiance.
Partner insists that some aspects of their money should stay private no matter what.
A spouse knows what their partner thinks up-front and doesn’t tell the truth.
Embarrassment about personal finances and hiding the truth from another spouse. A spouse doesn’t like being judged and does everything to avoid it.
Lack of communication about finances and fear that another partner will disapprove. One spouse might avoid discussing money because of fear of disapproval.
Avoiding arguing about money and upsetting other spouse. A spouse might hide financial decisions to prevent conflict and keep the peace in the relationship.
Indeed, a spouse committing financial adultery can use the above reasons to justify anything. On the other hand, they might not think about money seriously before saying “I DO,” promising transparency. In any case, you can lose your hard-earned cash.
The lesson?
BE CAREFUL!
Examples of Money Deceit in Marriage
You should know that financial infidelity can appear in many different ways.
It can be something as simple as using a credit card your spouse doesn't even know exists.. Or it might be a more serious deception, like secretly siphoning both spouses' money and using family members for safekeeping.
Additionally, you might deal with anything in between and, in more severe situations, a combination of a few offenses.
Scary, right?
Hiding financial information from your spouse is another example of financial infidelity. The 2021 Harris Poll identified several forms of financial secrecy, including hidden bank statements, bank accounts, and purchases.
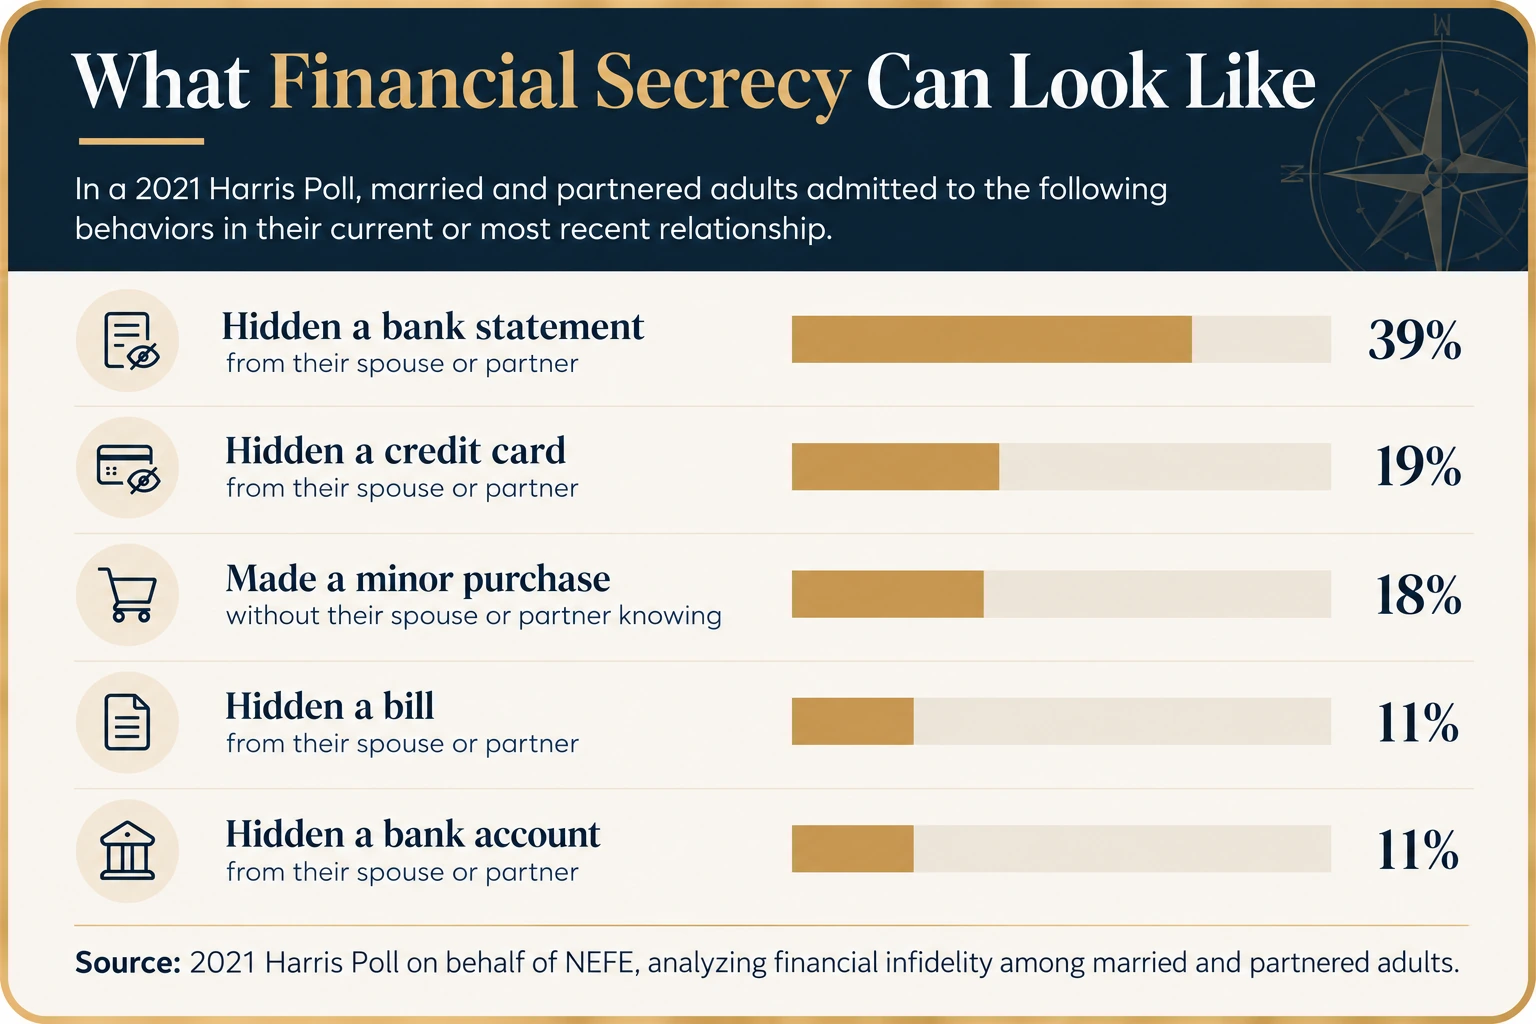
Further, your spouse might have secret bank accounts or credit cards. Here, it is very likely that your spouse has paperless statements and does all transactions online.
Another common form of financial infidelity is hiding cash or making purchases without your spouse knowing. Have you noticed unexplained expenses or extravagant splurges that don't fit your usual lifestyle?
Interestingly, current income level or homeownership status doesn't relate to financial deception. So, if you think that people with more money cheat more, it is not necessarily correct.
On the other hand, employed spouses (vs. unemployed) and households with kids under 18 are more likely to commit financial infidelity.
Another example of money deceit is when a person lies about how much money they earn, save, spend, and how they spend it. So, do you know exactly how much money your spouse makes? When last time did you see their paystubs?
But wait! There is more...
Financial deception can occur before marriage and the most serious example is when your partner lies about their income, assets, and debts in a prenuptial agreement, if there is one.
Signs of Financial Infidelity
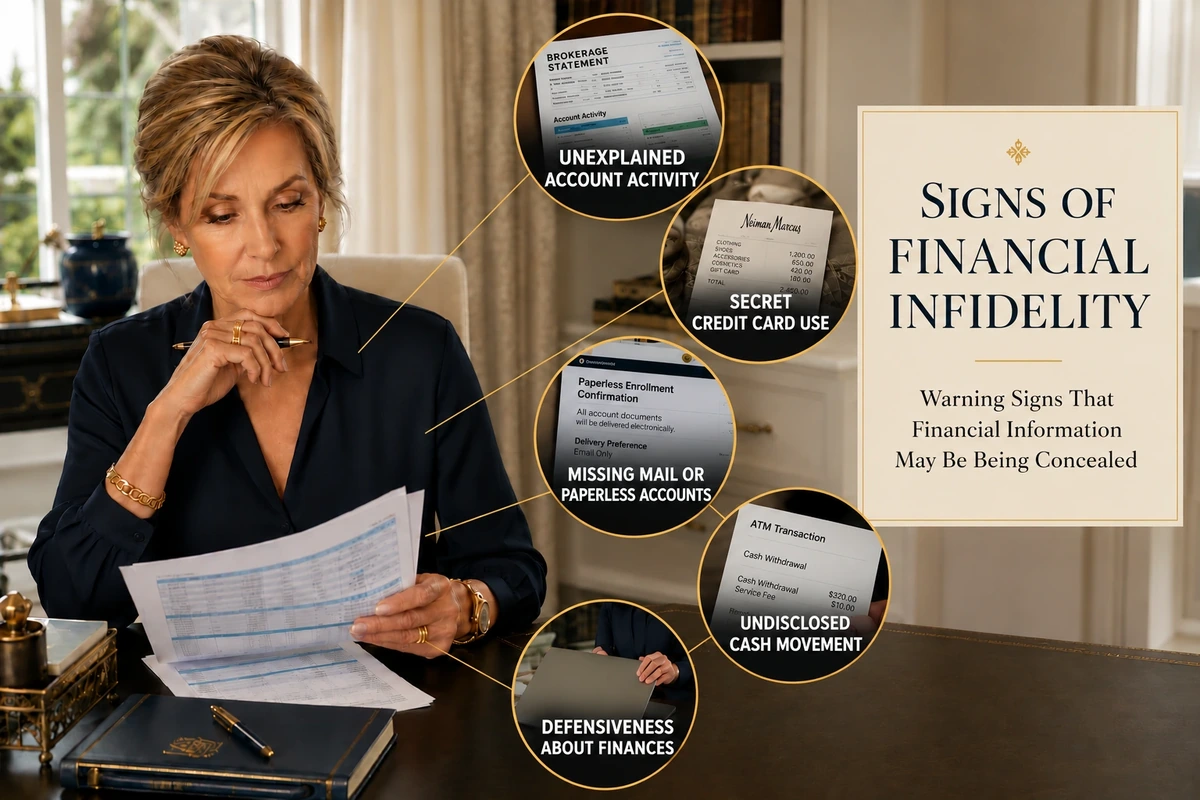
So, you suspect financial infidelity. It's time to put on your detective hat and uncover the truth.
Let's discuss the top signs that can help you recognize financial deception and what to do about it.
If you were my client dealing with financial infidelity, I would ask you the following questions:
1. When was the last time you saw and reviewed the bank statements?
As we've seen, hiding a bank statement is one of the most common warning signs of financial secrecy. That's why you should review bank statements and examine them carefully.
Specifically, look for any suspicious transactions or recurring payments that raise eyebrows.
2. How about your car insurance premium? Did it go up?
Most people don’t know that car insurance rates can go up for reasons other than an accident. In Florida, credit information may also affect premiums.
Your spouse might have credit cards you don’t know about.
Your spouse might be missing payments on those cards.
Of course, a higher premium alone doesn't prove financial infidelity. Check with your insurer first.
3. Is your mail being delivered regularly?
If you still get your financial statements by mail, be careful if your mail stops being delivered. One way to hide financial activity is to redirect statements to an office address or a family member's home.
A lot of people nowadays go paperless and handle their finances online. In this case, periodically check that you can still access your financial accounts online.
4. When was the last time you and your spouse talked about money?
Most importantly, you both need to have open and honest conversations about your finances. Ask questions, express your concerns, and pay attention to your spouse’s reactions.
Surprisingly, the truth reveals itself in the tides of conversation and speaks for itself.
5. Do you have a lifestyle that doesn’t match your earnings?
There are two possible extremes.
First, your spouse earns a high income. Do you have a nice lifestyle, or does your partner insist you be frugal?
Of course, financial planning and common sense matter no matter how much money you have. But it is suspicious when your partner insists on total control of all your money decisions.
On the other hand, what if your family lives beyond your means? Or does your partner have unexplained purchases or unusual spending habits?
In both cases, these patterns may be warning signs of financial deception.
6. Are you aware of all the debts you and your spouse have?
Using a credit card by one spouse when the other partner knows nothing about it is another common sign of financial misbehavior. As a result, your household could be taking on debt without your knowledge.
What to do?
Check your credit report!
Just as a lighthouse guides ships to safety, a credit report can illuminate debts or accounts opened in your name without your knowledge. Request a copy and look for unfamiliar accounts, balances, or discrepancies.
Go to www.AnnualCreditReport.com and get your free credit report from all three reporting agencies.
Of course, these red flags are only warning signs are just the alerts, and there might be more to the story...
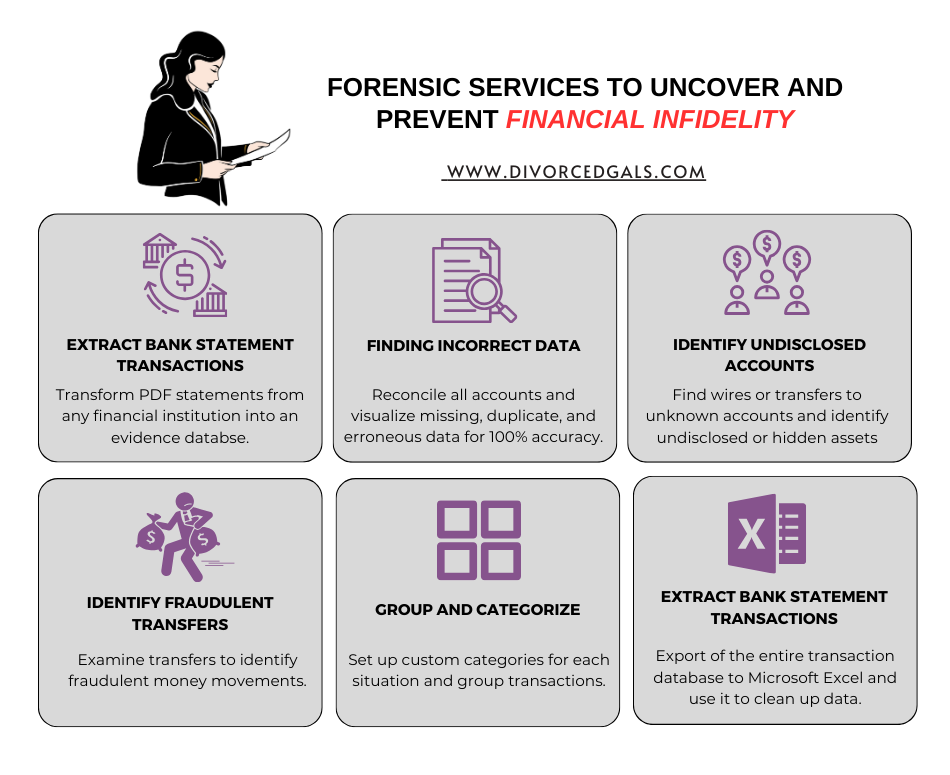
Explore our services to learn how we can help you identify financial infidelity and take steps toward financial recovery.
Financial Infidelity and The Law
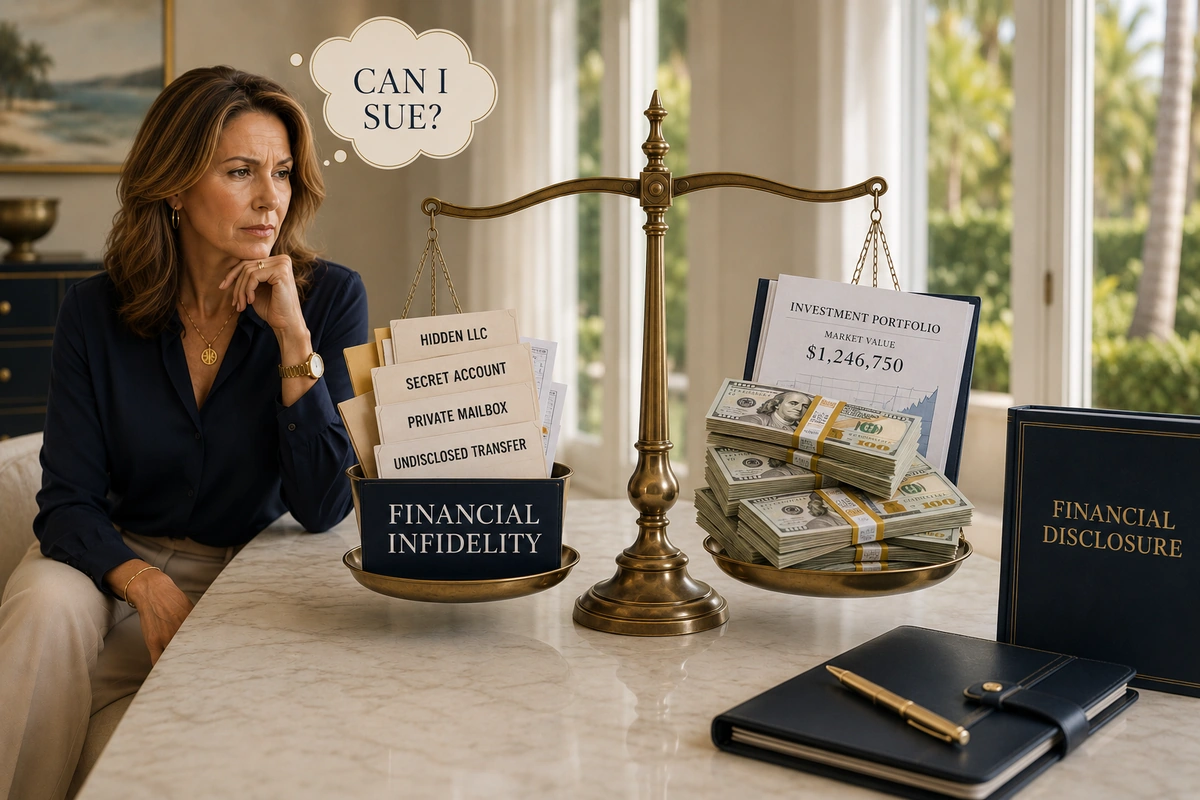
You may wonder if you can take legal action against your partner for their financial deception.
Can You Sue Your Spouse for Financial Infidelity?
While I am not a lawyer, financial infidelity alone doesn't necessarily give you grounds to sue your spouse. However, hiding assets, wasting marital funds, or concealing financial information can have legal consequences, particularly during divorce.
Also, it is reasonable to ask:
- Did you trust your spouse completely?
- Did you voluntarily surrender all financial tasks to them?
- Did you think trusting your spouse meant agreeing to everything they did with your money?
Of course, every case is different, and seeking legal advice is essential to understanding your options and protecting your interests. You may also have legal options for addressing financial misconduct during divorce.
Is Financial Infidelity Abuse?
In some instances, it can be a form of domestic abuse. WomensLaw.org suggests the following questions about how you are being treated. Specifically, does your partner:
- Steal money from you or your family?
- Force you to give them access to your bank accounts?
- Put you on an "allowance"?
- Force you to account for all the money you spend?
- Overuse your credit cards?
If you answered "yes" to any of these questions, you may be experiencing financial abuse"
Is Financial Infidelity a Reason for Divorce?
Maybe.
Sadly, in my divorce financial planning work, I see examples of financial betrayal in marriage over and over again. What's worse is repeated financial infidelity that could devastate you financially.
Of course, it all depends on what's at stake and how big the problem is.
If you are thinking about divorce, take our pre-divorce assessment and download a free pre-divorce checklist.
How to Overcome Financial Infidelity
But what if you want to save your relationship?
Although The Harris Poll found more negative consequences of financial deception, recovery is possible!
Financial Infidelity Impact
Weaker Relationship
- 42% - argument
- 32% - less trust
- 20% - less privacy
- 16% - divorce
- 16% - separation of finances
Financial Infidelity Impact
Stronger Relationship
- 19% - couple became closer and grew together
- 16% - have improved communication
Source: National Endowment for Financial Education, 2021 Harris Poll. Percentages reflect reported relationship effects among respondents who experienced financial deception in relationships with combined finances.
Let's discuss how to save your marriage after financial infidelity.
Should You Forgive Financial Infidelity?
First, remember: COMMUNICATION IS KEY!
Sit down, grab a cup of coffee, and have an honest conversation with your partner. Tell them how their betrayal made you feel, and see if you can work together to rebuild TRUST. It may be daunting at first, don't worry—we have a plan..
Curious?
How CDFA® Can Help You Recover from Financial Infidelity
Second, rebuilding a relationship after financial infidelity in marriage is a new phase of your life. For this reason, you must be vigilant. Without greater financial transparency, the same problems could happen again, potentially putting both of you at financial risk.
Can you afford it?
That's where professional guidance can help, especially with complex finances.. Think of it as having a financial professional help you navigate this uncharted territory:
- Creating a joint budget
- Monitoring expenses and debts
- Setting financial goals
- Managing cash flow
- Making financial decisions together
- Periodic review of all your financial documents
You can verify professional credentials through the Institute for Divorce Financial Analysts and connect with Nella Zelensky, a CDFA®, MAFF® (Certified Divorce Financial Analyst®, Master Analyst in Financial Forensics®).
In any case, YOU CANNOT EXPECT IF YOU DON'T INSPECT!
Hiring a CDFA® or MAFF® and conducting periodic financial reviews may be included in a couple's postnuptial agreement
Frequently Asked Questions
FAQs
Yes, it can. Florida follows equitable distribution, which means courts divide marital assets and debts fairly, though not necessarily equally.
If your spouse intentionally wastes marital funds, hides assets, or fails to disclose financial information, those actions may affect how the court handles your divorce settlement. However, financial infidelity alone does not automatically entitle you to a larger share of marital assets.
Start by reviewing bank statements, tax returns, credit reports, and other financial records you can legally access. Look for unexplained transfers, unfamiliar accounts, or missing income.
If you suspect your spouse is hiding assets, a divorce attorney can help you obtain financial records through the legal discovery process. A CDFA® or a financial forensic specialist, such as an MAFF®, can help analyze financial records and identify discrepancies that warrant further investigation.
Not necessarily. In Florida, a credit card debt incurred during marriage may be considered marital debt, even if only one spouse's name appears on the account.
However, responsibility for paying the creditor and how the debt is divided during divorce are two different matters. If your spouse secretly accumulated debt, a divorce attorney can help determine whether you have grounds to challenge its allocation in your settlement.
Start with bank and credit card statements, tax returns, pay stubs, retirement account statements, and mortgage or loan documents. Look for unexplained withdrawals, unfamiliar transactions, or inconsistencies between reported income and spending.
Keep copies of records you can legally access, and organize them by account and date. These documents can help your divorce attorney and CDFA® identify financial discrepancies and determine whether further investigation is needed.
Yes. A postnuptial agreement can help married couples establish clear financial expectations and decide how certain assets and debts will be handled if they divorce.
It may also address financial disclosure, separate accounts, and responsibility for future debts. However, an agreement cannot guarantee that a spouse will be financially honest. Both spouses should seek independent legal advice to ensure the agreement is properly drafted and enforceable under Florida law.
Final Thoughts...
Remember that financial infidelity can pose serious financial and emotional risks since it can disrupt your life and your relationship. That's why you should:
- understand reasons for money betrayal
- recognize signs of financial deception
- review your personal finances, including income, spending habits, investments, and debts
- discuss your concerns with your partner and prepare a recovery plan. However, if your partner uses financial abuse or coercion, prioritize your safety and seek independent professional guidance before making financial decisions together.
- monitor your money regularly
In the end, financial deception doesn't have to sink your marriage. If you work with your partner, you can become co-captains of your ship, navigating the vast ocean of financial bliss together.
But regardless of whether you stay married, go solo, or have a new relationship, GET INVOLVED!
And it is especially critical if you are a woman. Why?
Because even today, many women still leave financial matters to their partners.. That is an old stereotype, and that is WRONG!
Lastly, know that help is available. Our goal is not only to show you how to recover from financial infidelity. We will guide you into a more confident and prosperous financial future.
Are you ready?
For the life you're building,
Nella Zelensky
About the Author
Facing her own divorce, Nella discovered firsthand how overwhelming financial decisions can become—even with a background in finance. That experience inspired her to focus on divorce financial analysis. Building on an established career in finance, she earned the Certified Divorce Financial Analyst® (CDFA®) designation, followed by the Master Analyst in Financial Forensics® (MAFF®) credential.
Today, as Co-Founder of The Divorced Gals, Nella helps women understand the financial consequences of divorce, ask better questions, and make decisions with greater clarity and confidence.